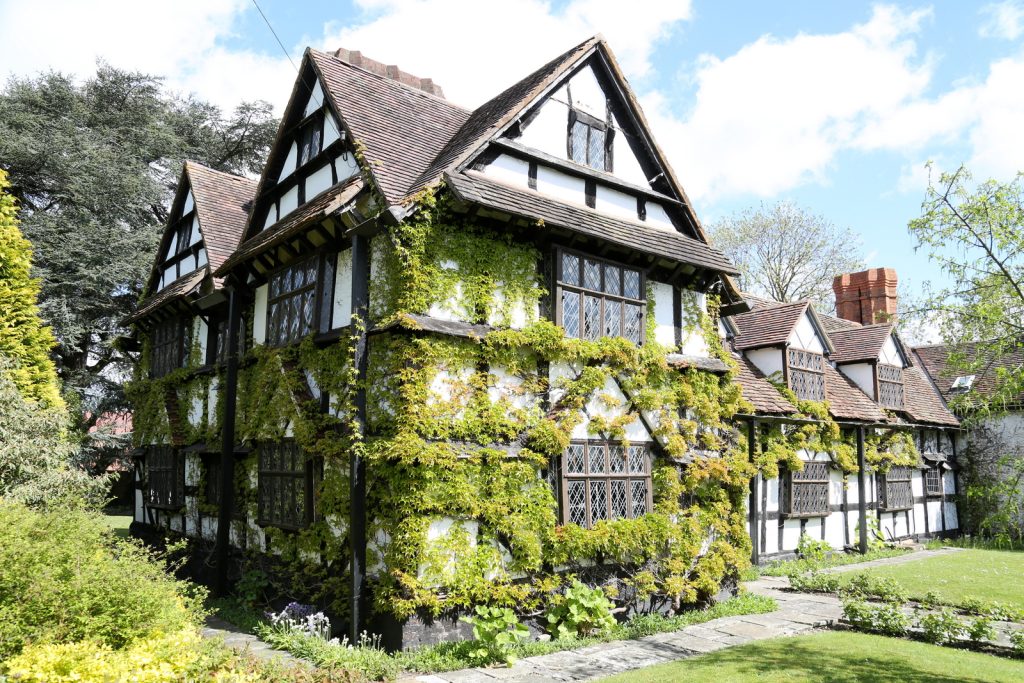
We are frequently asked questions about vat on listed buildings, or vat on listed building repairs.
It is true that there USED to be a 5% concession for ‘Approved Changes’ to a Listed Building. Even repairs were still charged at 20%. Accounting for a restoration project was a nightmare – changes had to be invoiced clearly differently to repairs. In October 2012, all this changed and the flat rate of 20% was applied to all work, whether approved changes or repairs.
So – vat and listed buildings is no longer an issue – it’s the same as for everything else. A great pity that new-build houses are zero rated, and Listed Buildings 20% – there isn’t really any incentive to repair and restore old buildings in preference to building new. It’s partly why so many older areas – city centre terraces for example, are bulldozed in favour of cheaper new-build.
The only time work is a lower rate, is when it’s newbuild, or the property is not on the Rating list, and uninhabitable. If its been unoccupied for more than 2 years, it is eligible for a reduced rate of 5% VAT.